

What if you don't need $5,000 a month in dividends to put your retirement income ahead of most retirees?
The number may be much lower than you think.
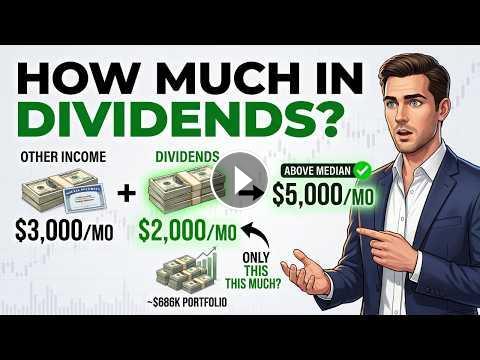
Recent Census data puts median annual household income for households headed by someone age 65 or older at approximately $56,680 or about $4,723 per month before taxes.
But that doesn't mean your investment portfolio needs to generate the entire amount.
Social Security, pensions, and other reliable income sources may already cover part of the target.
In this video, we'll use approximately $5,000 per month as a retirement-income benchmark and calculate how much dividend income a portfolio might actually need to provide to close the remaining gap.
We'll break down the Dividend Gap, compare $1,000, $2,000, and $3,000 monthly dividend targets, calculate the portfolio sizes that could support those amounts at an illustrative 3.5% yield, and examine why expenses and debt can matter just as much as gross retirement income.
Most importantly, we'll answer the question behind the title:
What monthly dividend income could actually put you ahead of most retirees?
What You'll Learn
• Why roughly $5,000/month is a useful retirement-income benchmark
• Why $5,000/month in total income does not mean you need $5,000/month in dividends
• How the Dividend Gap reveals what your portfolio actually needs to produce
• What $1,000, $2,000, and $3,000 per month in dividends could require
• Why $2,000/month in dividends can dramatically change the retirement equation
• How multiple income sources can work together through the Income Stack
• Why two retirees with the same monthly income can have completely different financial realities
• How reducing fixed expenses can improve retirement cash flow without increasing portfolio income
Chapters
00:00 You Probably Don't Need $5,000/Month in Dividends
02:21 The Number You're Actually Trying to Beat
04:38 Find Your Dividend Gap
07:00 What $1K, $2K and $3K/Month Actually Require
09:36 Why $2,000/Month Can Change Everything
11:52 Why the Same $5,000 Can Feel Completely Different
14:16 Lower Expenses vs. Higher Dividend Income
17:02 What Monthly Dividend Income Actually Puts You Ahead?
Sources & Concepts
Retirement Income Benchmark approximately $4,723/month based on median annual household income of roughly $56,680 for households headed by someone age 65 or older. This is household income, not dividend income, and does not exclusively represent fully retired households.
Retirement Income Gap comparing a target monthly income with income already provided by reliable sources.
Retirement Income Gap = Target Monthly Income − Reliable Monthly Income
Dividend Gap the portion of the retirement-income target that the dividend portfolio would need to provide.
Dividend Gap = $5,000 Benchmark − Other Monthly Income
Required Portfolio estimating the invested capital needed to generate a specific annual dividend target at an assumed portfolio yield.
Required Portfolio = Annual Dividend Income ÷ Portfolio Yield
Income Stack combining reliable retirement income with dividend income rather than requiring the investment portfolio to fund the entire retirement.
Spendable Income Gap comparing total retirement income with essential fixed expenses to understand how much monthly income actually remains available.
Income Equivalent illustrating how permanently reducing a recurring expense can improve monthly cash flow by the same dollar amount as generating additional income, while recognizing that the two strategies are financially different.
Portfolio calculations use a 3.5% dividend yield as an illustrative assumption. Dividend payments and investment returns are not guaranteed, and higher yields do not automatically represent safer or better investments.
#dividends #dividendinvesting #retirement #retirementincome #passiveincome #investing #personalfinance #dividendincome #financialfreedom #wealthbuilding #portfolio #retirementplanning
Financial Disclaimer
This video is for educational and informational purposes only and should not be considered financial advice. Investing involves risk, including the potential loss of principal. Always do your own research before making financial decisions.
Production Note
This channel uses AI tools for voice narration and visual rendering, but every video is originally researched, written, structured, and edited manually by the creator. The sketch-style visuals are designed to simplify complex financial ideas and make them easier to understand. This is a human-led project dedicated to high-quality financial education.
- Категория
- Пассивный доход
Комментариев нет.
Следующее
Auto
-
11:23

Work From Home/Remote Medical Billing | Can You EARN 100K+ Monthly Income? Truth, Skills & Jobs 2026
-
00:38
POV: You live in an RV but run a cloud architecture that puts most offices to shame. ☁️
-
22:58
The AI Workflow That Puts You in the Top 1% | Practical Steps to Level Up
-
13:26
Dividend Investing and 4% Passive Income Explained
-
00:27
The Dividend ETF Strategy For Passive Income
-
01:05
AI bây giờ công nhận đỉnh thật, tạo y người thật luôn =)))
-
00:26
Highest Yielding Dividend Paying Stocks in the S&P 500 If you love, passive income, like me then
-
00:55
How Dividend Stocks Create Passive Income and Long-Term Wealth | ADIB Wealth Management
-
27:06
These AI Hacks Will Get You Ridiculously Ahead of Most People (Q&A)
-
03:31
How to Build a $10,000 Per Month Dividend Income Portfolio
-
00:21
Сайты для заработка | Заработок в интернете 2023
-
10:03
Пассивный доход в 2024 с минимальным риском [Инструкция для новичков]
-
06:33
Где найти подработку ЗА ОДИН ВЕЧЕР? Работа онлайн в 2024
-
00:54
Как новичку начать зарабатывать на трейдинге в 2024 году?
-
11:05
Как ЗАРАБОТАТЬ ШКОЛЬНИКУ в ИНТЕРНЕТЕ ? Самые Лёгкие Способы заработка денег в интернете 2024 !
-
13:39
Как зарабатывать с ТЕЛЕФОНА в 2024 году? Лучший, проверенный способ
-
34:57
Лучший интернет-бизнес для старта в 2024. (Для новичков)
-
01:00
Как майнить криптовалюту с телефона?Мобильный майнинг! 3$ за регистрацию!Заработок в интернете !
-
12:28
ФРИЛАНС с НУЛЯ в 2024 году| РЕАЛЬНО ли ЗАРАБОТАТЬ?
-
05:59
Как заработать на Pinterest? Бесплатный Трафик о котором никто не говорит.
 Загрузка...